Showing posts with label Property Auctions. Show all posts

Sunday, 1 January 2012

Star homes: the top ten UK celebrity villages

Take a closer look at our most picturesque villages and you’ll see flocks of footballers, actors and models nestling in the undergrowth. With that in mind, we went in search of England’s top ten

Over and above the benefits of rubbing shoulders with the rich and famous over a pint at your local, having a celebrity neighbour in your village could actually increase the selling price of your home by five to ten per cent.
That’s the estimate of Simon Ashwell, Head of Savills Weybridge who says the buzz created by celebrities drives his local market.  “Does it add to the area? I would say, yes, it does,” he concludes. 
It’s a view shared by Knight Frank’s Judith Archer, used to handling celebs buying north Cotswolds bolt-holes from her office in Stratford-upon-Avon.  “It does make the areas more sought after, more fashionable…it adds that element of being a bit exclusive,” she says. “It’s amazing how word of someone living in an area can get around."
Most celebrity villages are clustered around beautiful well-connected areas that would attract a high price tag, but both Archer and Ashwell note that in the current market, homes with celebrity appeal are easier to sell.
Here’s out pick of England’s top celebrity villages in which to buy.
1. Kingham
Voted England’s perfect village several times over, Kingham, near Chipping Norton in Oxfordshire, is home to former Blur guitarist-turned-cheese-maker Alex James. Called Notting-on-the-Hill by locals, this unspoilt spot, with two hotels, one shop, and an excellent village pub, The Plough, is unique among villages in the district because of its direct train link to London. Daylesford Organic, grocer to stars like Kate Moss, Jeremy Clarkson and Liz Hurley living in nearby Cotswolds villages, is on the outskirts.
2. Alderley Edge, Cheshire
Alderley Edge in Cheshire, bristles with footballers and wags such as Rio Ferdinand and Gareth Barry. Named after The Edge, the National Trust owned cliffs that offer fantastic views across Cheshire and Manchester, it forms part of the Golden Triangle of villages that includes Knutsford and Hale popular with football stars like Mikael Sivestre, Wayne Rooney, Carlos Tevez, and Wes Brown.
3. Chalfont St Peter, Buckinghamshire
Chalfont St Peter, Buckinghamshire, near High Wycombe and Rickmansworth, is close to Pinewood and Elstree Studios,  Eton and Heathrow are a stone’s throw away and the train to London’s Marylebone is 30 minutes from nearby wealthy Gerrard’s Cross. The village takes in Chalfont St Giles and Little Chalfont, and is also the gateway to the Chiltern Hills. Noel Gallagher, Fern Britten, Cilla Black, Angelina Jolie and Brad Pitt and Ozzy Ozbourne all have homes close by.
4. Bucklebury, Berkshire
Bucklebury, Berkshire, leapt into the spotlight when Wills married Kate. It’s the home of Michael and Carole Middleton but its wooded country lanes are thick with secretive multi-millionaires who retreat to this beautiful country setting to ensure their anonymity. Other well-known figures who live close by include John Madjeski, Chris Tarrant, Kate Bush and Melinda Messenger.
5. Cobham, Surrey
If you visit Starbucks in Cobham, Surrey, on any given morning, you’re bound to see a Chelsea footballer – or a wag.  Former Chelsea manager Jose Mourhino stipulated players should live no further than fifteen minutes from the club’s football practise ground and it’s a legacy that continues today.  Dubbed England’s Beverly Hills, along with nearby Oxshott, the area is home to Frank Lampard and John Terry, as well as Eamonn Holmes, Andy Murray, Freddie Flintoff and Peter Andre.
6. St Georges Hill, Surrey
Up the road, St Georges Hill, Surrey, attracts a different sort of set.  In the 1960s it was a great escape for John Lennon, Ringo Starr, Cliff Richard, Elton John and Tom Jones.  These days the 3.9km squared private estate is full of Russian oligarchs and Bollywood stars, not to mention City financiers – former HSBC boss Michael Geoghan lives there, as well various telecommunications chiefs. With excellent connections to London, Heathrow and the countryside, it’s an ideal hideout for a high-flyer.
7. Walberswick
Walberswick, a tiny, picturesque fishing village in out of the way Suffolk, is the ideal location for celebs escaping the limelight. Linked to neighbouring Southwold by a footbridge spanning the River Blyth, it’s been a bolthole for screenwriter Richard Curtis, (Four Weddings and a Funeral, Love Actually) and partner Emma Freud. Michael Palin started up Southwold Electric Picture Palace and Twiggy, Gary Lineker, Griff Rhys Jones, Alan Rickman and Bill Nighy have homes in the area. 
8. West Wittering, West Sussex
With a beach hut fetching £60,000 from local resident Keith Richards a few years ago, West Wittering, West Sussex, is firmly on the celeb-friendly map. The beautiful seaside town 6.5 miles south of Chichester is loved for its long sandy beach and Nicholas Lyndhurst and Michael Ball also live in the village. Inland, nearby Midhurst and Pulborough are thick with polo ponies and sports cars, not to mention secretive celebs, who flock to these villages with views of the South Downs and good connections to London and Gatwick airport.
9. Salcombe, Devon
Everyone loves a good beach house and there are few better places to be on the Devon coast than Salcombe. Be prepared to cough up £500,000, though.  That’s the average house price in this quaint spot, beloved by Sir Michael Parkinson, Kate Bush and Sir Clive Woodward, making it one of the most expensive places to live in England outside London.
10.  Ponteland, Northumberland
Newcastle footballers head to Ponteland, Northumberland one of England’s wealthiest villages, just on the outskirts of Newscastle-upon-Tyne.  Darrass Hall is the exclusive estate to which the likes of Alan Shearer, Chris Morgan and Steven Taylor flock. Meanwhile, further north, Pippa Middleton could be bringing along the Glosse Posse when she visits her old flame George Percy, son of the Duke of Northumberland, at Alnwick Castle.

Star homes: How a rock legend can make a property more valuable

Fancy living down the road from The Beatles’ old flat? Turns out lots of people love to live in rock'n'roll localities and their music connections can add to an area's popularity and value, as Pierre De Villiers discovers

They may have a reputation for wrecking rooms, but when it comes to making homes more desirable, rock stars are in a league of their own.
Mention that a flat or house on the market was once occupied by a music icon, and potential buyers happily queue around the block. “Buyers are often attracted to the idea of living somewhere connected to a celebrity – particularly if it has been their home,” explains Peter Bevan of Sotheby’s International Realty. “Having a famous owner is certainly an immense benefit when promoting it.”

In 2008 Sotheby’s had the opportunity to promote one of the most famous flats in the world. Located on the fourth floor at 57 Green Street in Mayfair, Flat L was occupied by The Beatles in 1963 – the only time the Fab Four all lived together. While the home was sold for a large sum in 2009, the building’s status as an important part of Beatles history has made other flats at 57 Green Street hot property.
“The fact that The Beatles lived in the building is such an interesting piece of history,” says Charles Lloyd of Savills Mayfair who is looking after the sale of a two-bedroom flat at 57 Green Street. “It’s a bonus and a point of interest that buyers can tell their friends about.”


A property made famous by musicians not only boosts sales in the building but gives the surrounding area a lift as well. For rock and pop fans, purchasing property in Mayfair is like buying a stairway to heaven with Jimi Hendrix having lived at 23 Brook Street and the Bee Gees at 67 Brook Street.
“If a rock or pop star is connected to an area it can enhance its prestige,” says Bevan. “Locations such as Mayfair have long lasting star appeal that supports its intrinsic desirability.”

The fact that Freddie Mercury lived at 1 Logan Place in Kensington has certainly had a positive knock-on effect on other properties in the area. “We recently sold the property right next to 1 Logan Place and we had a lot of potential buyers asking about the Freddie Mercury house,” says David Terrar of Bective Leslie Marsh. “People found it fascinating that such a big star lived next door and would certainly pay top dollar for a place nearby.”

With so many people enamoured with star musician homes, many estate agents are happy to tell potential buyers where a property fits into London’s rich music history.

Frank Harris estate agents highlight the fact that Bob Marley lived at 34 Ridgmount Gardens in Bloomsbury, where they are overseeing the sale of a four-bedroom flat, while the link between Cheyne Walk in Chelsea and The Rolling Stones is played up by Chasemore Property. “I’m really keen to tell people about the role that Cheyne Walk played in the lives of The Rolling Stones,” says Suja Thomas of Chasemore Property, who promotes properties in a street nicknamed ‘Rolling Stone Row’ after Mick Jagger, Keith Richards and Ronnie Wood all lived there at some stage. “It’s nice to think you can own a property in a place that was so liked by a famous rock band. It makes the area seem even more special than it already is.”

Thursday, 29 December 2011

Room for improvement: Is it time to buy a student home?

With more than a quarter of a million students about to start university, buy-to-let investors are turning their gaze to student housing. Graham Norwood investigates if now is the time to invest

 
It may be holiday season for most of us but many teenagers and parents are working hard to find digs, a hall of residence or even a home to buy for the duration of a college course.
Some 240,000 young people will start university this autumn, bringing the total of students in the UK to 1.7m. The sector is growing, too, despite controversy over fees and loans.
“Student accommodation has outstripped the mainstream housebuilding market by every measure since the downturn - by its growth, rises in value, rent increases, and the number of people it houses,” says Marcus Roberts of Savills’ student accommodation division.
He negotiates with developers and university chiefs to create joint ventures, constructing sophisticated new-build students’ flats on campuses of the major colleges.
But the number of students far outweighs the number of these purpose-built units. “We're not talking about a demand of just two students to every bed - we're talking five, six or seven” says Savills’ researcher Jacqui Daly.
Therefore many colleges are thankful for buy-to-let landlords and parents who buy houses and turn them into student lodging.
The usual route is purchase a terraced house with three to five bedrooms, replace at least one reception room with another bedroom, and let out to students. A lettings agent costs 15% to 20% of the rental income - this sounds a lot but it is tax-deductible and means the agent finds and vets students, collects rent and deals with problems on your behalf.
But owners must be aware of red tape. If you let to five or more students, not in the same family and in a home of three storeys or higher, you may need a local authority licence as a House in Multiple Occupation (HMO), costing £1,250 or more.
There is wear and tear, too - higher with students than other tenants. Your house should include paving instead of a lawn, and easy-to-replace floors, worktops and cupboard doors. A bike shed prevents unsightly (and decor-damaging) bikes in the hallway.
This sounds like hard work but if you get it right the rewards are high.
Mike and Susie Randall from Exeter have a son, Andrew, finishing his second year at Loughborough University. They converted a Victorian terraced house in the East Midlands town in 2009 and are delighted with the result.
"It's clean and safe for Andy and allows peace of mind for us. We're amazed at the rent - £400 a week in term time after the agents' fee is deducted. Loughborough prices are pretty depressed so there's been no capital appreciation, but we intend to keep the house on after Andy leaves next year" explains Mike, a wedding shop owner.

Houses ripe for student conversion:

Lampeter has become one of the most popular colleges in the University of Wales. This five bedroom house could accommodate six or seven students. It costs £215,000 from John Francis


Swansea is a popular university: perhaps because its campus is next to the water and a beach. This house at Brynmill, near the city centre, has five bedrooms and is up for auction with a guide price of  just £90,000 with John Francis


Useful websites:
Get rough ideas of student rents on: http://www.accommodationforstudents.com/; http://www.studentaccommodation.org/; http://www.homesforstudents.co.uk/.

Why Phil Spencer’s on a mission to help first-time buyers

Phil Spencer’s new book is a toolkit for first-time buyers. He talks to Samantha Baden about his own attempts to get on the property ladder, his children’s home-owning chances and why he’s switched to presenting a holiday show


Phil Spencer is on a mission to help first time buyers. One-half of the UK’s most famous TV property couples, Spencer this week published his second book and it’s aimed at first-time buyers - the group struggling the most to buy a home.

Spencer and on-air partner Kirstie Allsopp have spent the past ten years travelling around the UK helping people buy property. But as Spencer says, the challenges faced by first-time buyers are now having a trickle-down effect on all homeowners, who are finding it hard to move up the property ladder as those lower down struggle.
What was your experience as a first-time buyer? Did you make a good investment?I did actually. I was very clear about my motivation at the time: I knew it was a first-time buy and wasn’t going to be my forever home. It was on a busy road in Battersea and I was 29 and it wasn’t even somewhere I even particularly wanted to live. But I bought the property purely for its ability to make money. I ended up living in it for five years. 

I knew it was in an area that was changing and that was going to change during the time I lived in it. So I bought it purely to help me climb up the ladder and I was lucky enough to be able to take two  steps up the ladder when I sold it because the market changed when I was there.

You’ve got two sons aged five and seven. Do you worry about their ability to buy property?Yes, in actual fact I was very concerned about that. When they were born, I cast my mind forward and wondered if they would ever be able to buy a property and how much a home might cost them when they leave school? It could be a million quid. So I made quite serious efforts when they were born: I bought one property when Jake was born and then another one when Ben was born two years later. Those properties will never be for sale because they are Jake and Ben’s. They’re in the same street as each other in Brixton.

If I can do nothing else for my children it will be to hang onto those and as and when they leave home they can either live in them or rent them out. I’d like to help with that.

Why is you new book focused on first-time buyers?My first book was about adding value at a time when it was increasingly important to add value to a property because the market wasn’t doing anything to help you. But what is very important and crucial in the market at the moment is that first-time buyers are the sector that are struggling the most. They are massively important to the health of the market.

Why are they so important?The market can be driven in two ways – by cash arriving at the top of the market and coming down through the market or by first time buyers joining the bottom end of the ladder and helping every body else shift upwards.

Where we are today, there’s not much cash arriving at the top and there’s not many first time buyers managing to get onto the bottom. I wanted to write a book to help these people at the bottom of the market because they’re crucial to every homeowner in the country.

As you say, it’s a difficult time for first-time buyers. What would improve the situation for them?What’s limiting their ability to get on the property ladder is access to finance. The Government has come up with their FirstBuy scheme, which will help 10,000 first-time buyers. It’s a step in the right direction, but 10,000 people is really a tiny number and it’s only being offered to those who are buying new builds, although I understand the reason for that.

So what else can first-time buyers do to get help?Buy the book and be prepared for the decisions they’ll need to take! Being a first-time buyer is such a daunting experience: it’s the biggest financial decision of your life, but there is precious little help out there for you at all.

For instance, too many first-time buyers go into an estate agent with the misapprehension that they’re about to be helped and provided with a service and with advice. But that’s not true. Estate agents are there to provide a service to the people who are paying their bills - the people who are selling their property.

So would you like to see a similar situation to what happens in the US with the use of buying agents who are there to look after the interests of the buyer?I would actually. I’ve been a buying agent for 15-odd years. We have a rather biased method of buying and selling property in this country – all the help is for the seller and the person spending the money is left to fend for themselves. Buying a home is daunting and it’s never more daunting than when you’ve never done it before as a first time buyer.

Given it’s so difficult to get on the market, are we in danger of becoming a nation of renters?I don’t actually. I think owning property is so deeply ingrained in our society and culture that I can’t see a day when that will change. I understand that’s not the case on parts of the continent and I can see that if a property isn’t going to rise in value then some of that motivation for owning is diluted.

But the fact remains: An Englishman’s home is his castle. We like to own our own homes and feel that’s why we go out to work and make sacrifices. We want to own our own bit of England and do with it  what we want, be there as long as we want and not have to move out when a landlord tells us or puts the rent up.

You’ve diversified with your new television show Vacation Vacation Vacation. Is property still your first love?Yes of course, but who doesn’t love going on holiday? Kirstie and I spent the past ten years travelling around England and staying in hotels and exploring new areas and looking for deals for people. The Vacation idea came out of that, just on a bigger scale and with a focus on holidays.

Holidays are of course another big financial decision. In the same was that a house doesn’t always suit all members of a family and there are compromises and decisions that have to be made, the same is true of a holiday when one family member wants to do lots of activity and one wants to lie still.

So with all this travelling to exotic destinations, were you tempted to buy property overseas?Property is such a big investment and it’s difficult in any market to invest wisely. So I believe you should invest only in a market that you know and understand. I know a fair bit about the Australian property market and I have looked at property in Ibiza because I’ve been there a lot, but to answer your question no I wasn’t.

I think some people fall foul of that when they are choosing a home, an investment or a holiday home. There are different motivations and you chose different properties for each option and these competing motivations in an unfamiliar market can muddy the water.

What’s your top piece of advice for first-time buyers?Try to choose a property that will suit you for the longest possible period of time. First-time buyers tend to be at a stage in life when things can change quite quickly – where you work, where you live and who you live with. So buy a home that is flexible enough to suit as many of those options as possible.

Also, try to chose a property that you can add value to during the time that you live there. And I say that because the market isn’t necessarily going to help you move in the future, certainly not in the same way as we’ve seen in the past ten years, so it’s now harder to generate equity to help you move and come up with a deposit for your next home. Chances are you’ll have to come up with that yourself.

But what about the push for first-time buyers to buy new build homes? It’s much harder to add value to a new build.
Yes, it is much harder, nigh on impossible, to add value to a new build unless the area changes. However it can be easier to raise the money because there are more schemes out there to help you do that to buy a new build. On the other hand, an older property can be harder to buy because it might be in a chain and cost more money, but you do get the opportunity to add value to it. It's a tricky one.

Surveys and valuations: A beginner’s guide

Surveys and valuations are crucial if you’re buying so it’s important you’ve got a grasp of what they mean and why you should bother

 
Getting the home you want to buy surveyed is an important step in the journey toward buying a property, but for those who’re unfamiliar with the property market it can be a confusing time. If you're getting a mortgage then your lender will do a survey for valuation purposes, but you may also be asked whether you'd like an additional survey. While it doesn't always make sense (for example if you're buying a new build from a reputable developer), a survey could turn out saving you a fortune in the long term.

What is a survey?
  Richard Sexton of e.surv chartered surveyors says mortgage valuations are not the same as surveys.
"It’s a common misconception that many buyers have a ‘survey’ as part of their mortgage application," he says. "This isn’t the case, as mortgage lenders will only instruction a 'mortgage valuation' for their own lending purposes."

Unfortunately many people are under the impression that the valuation their mortgage lender organises will highlight any underlying problems there may be with a property, but that’s just not the case. Sexton says this leaves customers who do not instruct their own survey report with incomplete information about the true condition of the house they are purchasing.

Why is it important to get a survey? 
 It’s simple really. When making any purchase, the more you know about the product the more easily you can decide if it’s worth buying. The same goes for buying property except the consequences of making a wrong decision, perhaps due to lack of information, can be far more damaging.

Sexton says those who have not obtained a survey frequently uncover issues when they move into a new home. Getting a survey completed on a property, as early as possible, allows for any problems to be identified and action taken sooner rather than later.  "Ultimately it can avoid delays, late price negotiations and even the heartache of a sale falling through or missing out on another property that may have been more suitable," he says.

What are the different kinds of survey report? Sexton says there are three main survey report types available:
 
RICS Condition Report 

The report is a survey which includes an inspection of the property and there is also a section which provides advice for solicitors and a clear summary of the key risks associated with the purchase. It does not include a valuation.

RICS HomeBuyer Report 

This is a more detailed report where a chartered surveyor will undertake a thorough inspection of the property so that any defects that might not be identified in a mortgage valuation report will be noted. This survey format does include a valuation within the report.

Building Surveys 

This is a very detailed report. The surveyor will examine closely the structure and condition of the building and in some cases may recommend specialist reports for drainage, electrical systems, central heating and timber infestations. The inspection may take several hours and involve some limited disturbance of the building itself. A building survey is considerably more expensive than any other type of report in recognition of the work involved. A building survey will not normally include a valuation but this should be requested at the time of instruction if required.

How much can I expect to pay for a survey? 
 Private surveys are an additional expense but they often cost less than 0.5% of the property’s value, says Sexton. Typically, a basic survey can cost from £200, however most survey costs are tiered depending on the cost of the home you are buying and the level of detailed information you opt for.
"The average repair costs identified by private surveys is £1800, making them a great way to offer real value for money and help you understand the true costs associated with your purchase," Sexton says. "It is possible that many prospective purchasers will be able to successfully renegotiate the purchase price based on the information contained in their survey report."

How to: work out if you're better renting or buying

We talk to people who have tried (and succeded) to get on to the property ladder aided by a decent deposit. How much would you need?

 
Caroline Smith and partner Dan Goodwin, both 27, have been renting together for 18 months, but have now seized the moment to get on the housing ladder, buying a one-bedroom flat in Guildford, Surrey.
They join the ranks of rising numbers of people applying for a mortgage – with more of us on the move now the impact of recession is easing.
"A lot of people think that it's a landmark event, but it just feels like we've entered into a more complex rental agreement," she explains.
"We started off on comparison websites, but we also went to banks' sites and played around with their mortgage calculators.”
Caroline explains that, after seeking help from mortgage advisors, she and Dan, both web analysts, opted for a repayment loan fixed at 5.74%. "We spoke to a loans advisor who said that our deposit fell at about 12%, and she recommended that we try to get 15% so that we could get the rates down a little bit.
"We went with a three-year fix because two years didn't seem very long - but five years seemed a bit like 'whoah!'; a lot could happen in five years. We chose to fix because it was more important to us to have peace of mind; knowing what was going out of our account each month."
But Adam Hassan, from Brighton, also recently stepped onto the housing ladder, has a different experience. "My partner had an inheritance so we had a good deposit. She paid 50% up-front, so that easily allowed us to get the best mortgage rates.
"We got 2.2%, and opted for an interest-only tracker loan. In the current market I don't think the rate is going to go up too high. At this point there's no point trying to fix because lenders put an extra one or two % on it.
"I chose interest-only because although I will make overpayments to repay the loan, if times get tough I can just pay less - the flexibility is  fantastic."
Shop around: Some lenders are more competitive than others and the rates on offer vary dramatically. Look at several lenders' rates, and consider a mortgage advisor if you're struggling to understand the details.
Beware of hidden costs: Look beyond the interest rate and consider any setup and termination costs. For flexibility, check whether features such as payment holidays or overpayments are available.
Moving home is expensive: Remember to budget for essential home improvements, home insurance, for legal fees and the cost of moving itself. The 2010 budget introduced Stamp Duty relief for first-time buyers choosing a property worth up to £250,000 – a welcome relief.
Don't rush: It's easy to feel pressurised when buying a home, but a mortgage is one of the most important financial decisions you can make. It's essential that you understand what you're agreeing to and that you can afford it - now and in the future.

Repossessed Property Auctions - A Buyer's Guide

Auction houses are seeing a significant increase in the number of repossessed properties for sale at auction. But is a repo always the best buy?...

For some first-time buyers, would-be property investors, and professionals alike, the words "by order of receiver for mortgages" are enough to get their pulses racing.
The chance to buy a repossessed property for sale at auction at as little as 60 per cent of what the mortgagor originally paid is certainly hard to ignore.
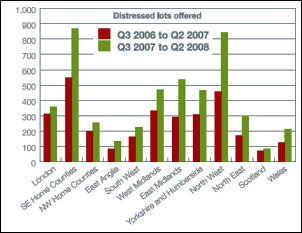
And, according to figures from Essential Information Group (EiG), the volume of
repossessed property
 appearing at auction has risen by 100 per cent over the past 18 months, so it should be an ideal time to start bidding. But is it quite so simple?
Bargain Bidding At Repossessed Property Auctions

David Sanderman, from Essential Information Group (EIG) which tracks every house that goes to auction in the country, says that you can’t assume you’re getting a bargain. "A lot of people think if you buy a repossessed property it’ll be cheap. But if you have two flats, one of which is a repossession, one, not both could sell for the same money. A property will get what it’s going to get." 
The obvious attraction in repossessed houses and flats is, of course, the temptingly low reserve, reflected in the guide price.  
It’s low because although the lender has a duty to sell at the best price, time is money, and they will want to recoup their funds as quickly as possible.
The problem for a potential auction buyer is that a low guide price may attract so many interested parties that it results in a higher sale price. 
In fact, it’s possible that you could find yourself paying over the market value because, according to David, there are many people who will be at an auction specifically with repossessions in mind. 
So, are repossessed properties likely to be bargains? Yes, but only if no one else has noticed them and is bidding against you!  

Wot No Bidders?

The good news for bidders is that there are fewer people willing to part with their money at auction than a year ago.
The EIG figures for August 2008 show that although the number of lots offered to auction was up slightly on last year, the number of sales achieved was only 55 per cent, down 14 per cent on August 2007.
Simon Zutshi, founder of Property Investors Network says: "Someone I know who went to a property auction recently told me that out of 30 lots only one sold."
But, says Simon, this is good news for serious investors.
"Previously auctions haven’t been a great place to get bargains because there were lots of amateurs who were willing to pay too much.

"But once again they’re a good place to find deals either before, during, or after the sale."


The latest RAPID report from EIG and Allsops bears this out and suggests that more repossession bargains will emerge in the months ahead:
"Despite the rapid increase in numbers of distressed sale lots, a significant proportion of repossessed properties offered at many auction houses remains unsold. 
"This is largely due to overpricing in an increasingly weak market. 
"We anticipate that the success rate will improve as lenders face up to the need to price attractively to achieve results in the face of the inevitability of rising numbers of loan failures and increasing net monthly possessions over sales.

Des Res or Repo Property Disaster?

If you decide to try and bag an auction repo, what kind of properties can you expect to find?  
According to Essential Information Group (EiG) the type of homes sold at property auctions has changed recently, with smaller lots, particularly flats, more prevalent. 
In terms of condition, David Lawrenson, who runs the property training and education company Letting Focus, says prepare yourself for the worst.  
"In general it would be most unlikely to find a repossessed home that’s spankingly clean and tidy! Repos may be in a bad state, but you can assess that when you go and view." 
But more importantly, as with any properties sold at auction, they may have serious structural or legal issues. "For the uninitiated, property prices at auctions seem low, but there is usually a good reason," warns David. "Many properties are in poor condition, have subsidence, are blighted by proposed road developments, have been occupied by squatters, have sitting tenants, or have defects in the legal title. Or they may just be unique and therefore hard to value." 
That said, auction houses are also seeing a lot of new-build properties coming under the hammer, and these may well be in much better shape.

How To Find Out About Repossessions?
There are over 200 property auctioneers in the UK, so registering with them all may be a little time consuming.  By signing up with local auctioneers you will receive details of relevant properties. However, regional homes are sometimes auctioned in London or other large cities, where they will probably attract less interest and may achieve a lower price. 
For the full picture, the excellent EiG property auctions website covers all UK auctions and allows you to search specifically for repossessions.
 
Other Ways To Find A Repossession?
The thrill of auction day isn’t for everyone, but there are other, less blood-pressure-raising ways to find and buy repossessions.
1. Ask your local estate agent
Potential auctions properties are usually offered to estate agents first, so invest some time building a relationship with your local estate agents so they see you as a serious buyer if a property comes up in your area.
Also, keep a lookout in the local papers for properties asking for ‘best offers’ by a certain closing date.
2. Buy before the sale
Many auction properties will be open to offers before the day of the sale. Look out for sales details that state ‘unless previously sold’. If you’re lucky you may be offered a repossessed property at little more than the reserve price.
3. Buy after the sale
If a property doesn’t sell the auctioneer will often have the vendor’s authority to sell it at the reserve price for up to 24 hours after the auction.


Caveat Emptor
As with any property for sale at auction, it’s a case of buyer beware, so do your homework.
The legal side of the sale should be straightforward when buying from a lender, but beyond that it’s down to you to check that you know exactly what you’re buying and that you’re ready to do business.


1. Go and see the property: You may have to go as part of a block viewing, but at least you’ll see your fellow bidders.
2. Paper Work: Before the day, get the property surveyed and legal checks completed. Be on the lookout for special conditions in the memorandum of agreement.
3. Finance In Place: Have the mortgage and insurance ready. You’ll only have 28 days to complete, and delays could lose you the property and your deposit plus the cost of re-auctioning it.
4. Deposit: You’ll need to pay a ten per cent deposit when the gavel falls, so make sure you have it with you.
5. Keep Your Head: Decide how much you’re willing to pay and stick to it.
Advice for People Facing Repossession
If you are having trouble paying your mortgage bills you shold act quickly to avoid repossession. For more information and advice, visit:
  • Consumer Credit Counselling Service
  • Citizens Advice Bureaux

Michael O'Flynn
Related stories: 
A Guide to Buying at Auction
If picking up a bargain really gets your juices flowing, then buying a property at auction may be just the thing to send the adrenalin coursing through your veins...
Sealed Bids: A Buyer's Guide
Gone are the days when an asking-price offer secured the house of your dreams. Today you may have to compete in a nerve-wracking sealed bid auction...
Estate Agent Fees: A Beginner's Guide
Estate agents' fees - it's hard to avoid them, but understanding the lingo and reading the small print can save you serious cash...